Politics & Society
Life or Debt: The Stranglehold of Neocolonialism and Africa’s Search for Alternatives
Many countries across the Global South, particularly those in Africa, are currently in the throes of fiscal crises. The Third World must re-imagine a path out of our current crisis that doesn’t depend on the IMF, its allied institutions, and Western capital. The last seventy years or so have demonstrated that a reliance on these institutions only serves to trap the Third World in a perpetual state of underdevelopment.

Dossier no 63
Tricontinental: Institute for Social Research
April 2023
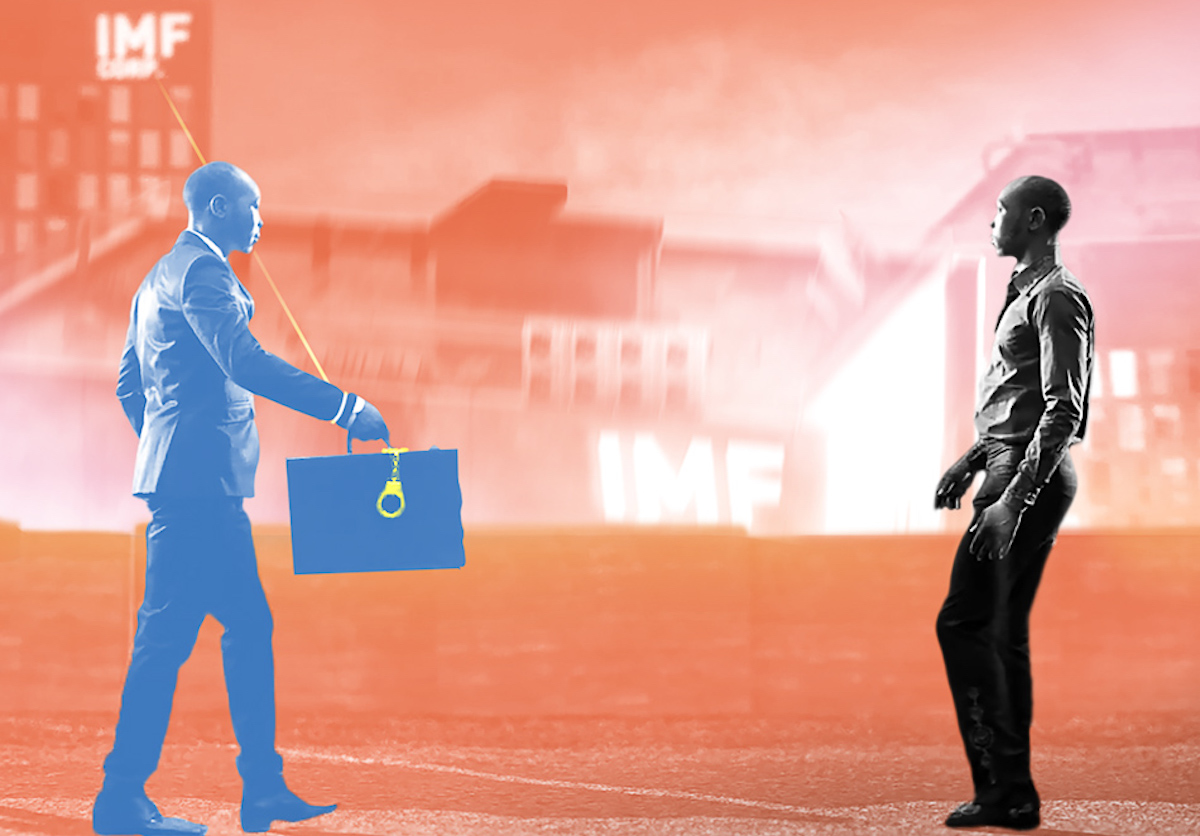
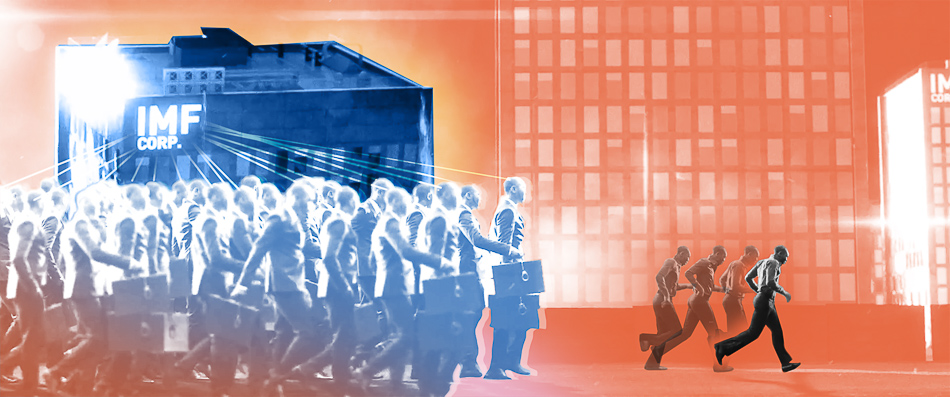
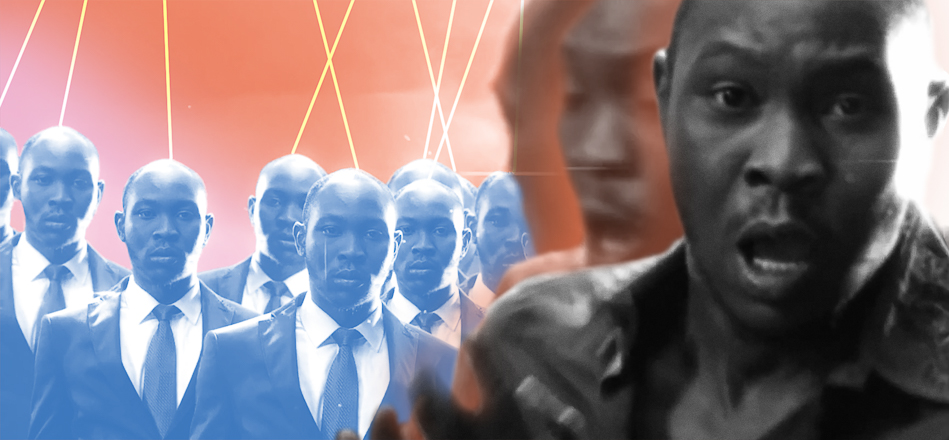
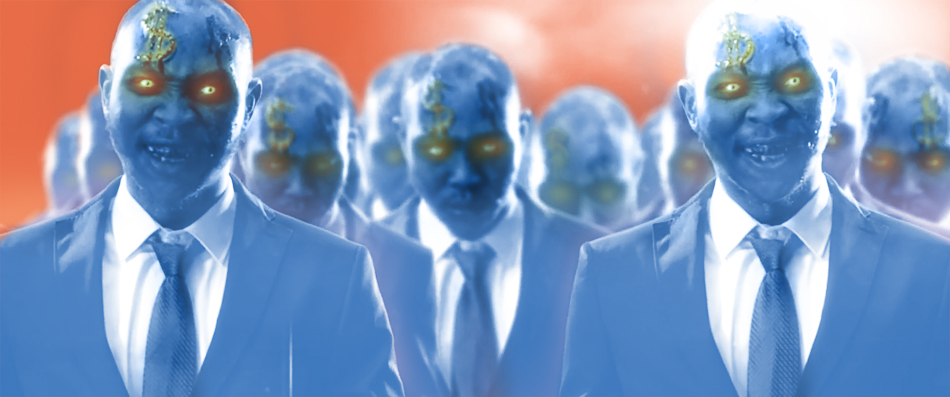
The art in this dossier is based on still frames from the music video ‘IMF’ by Seun Kuti and Egypt 80 (Knitting Factory Records) featuring Dead Prez’s M1, directed by Jerome Bernard and produced by Duck Factory.
Seun Kuti is a member of the band Egypt 80 and the youngest son of the late Nigerian Afrobeat pioneer and political figure Fela Kuti, whose popular album Zombies, released in 1976, heavily criticised the military dictatorship that was in power at the time and inspired resistance among the Nigerian people. Nearly forty years after the release of his father’s album, Seun’s music video ‘IMF’ harks back to the continued assault against the sovereignty of the African people, featuring rows of growing zombie-like International Monetary Fund (IMF) officials chasing an African man and, finally, turning him into a money-obsessed, disfigured monster identical to themselves.
Before the pandemic was announced by the World Health Organisation in March 2020, the poorer nations of the world already struggled with seriously high – and unpayable – levels of debt. Between 2011 and 2019, the World Bank reported, ‘public debt in a sample of 65 developing countries increased by 18 percent of GDP on average – and by much more in several cases. In sub-Saharan Africa, for example, debt increased by 27 percent of GDP on average’.1
The debt crisis did not take place because of government spending on long-term infrastructure projects, which could eventually pay for themselves by increasing growth rates and allow these countries to exit from a permanent debt crisis. Rather, these governments borrowed money upon borrowed money to pay off older debts to wealthy bondholders as well as to pay for their current bills (such as to maintain education, health, and basic civic services). ‘Among the thirty-three sub-Saharan countries in our sample’, the World Bank noted, ‘current spending outstripped capital investment by a ratio of nearly three to one’.2 When the pandemic struck, countries that had adopted the World Bank-International Monetary Fund policy to grow their way out of the debt crisis floundered. Growth rates shrank, which meant that debt volumes ballooned, and so these governments decided to borrow more and adopt deeper austerity policies, which dramatically increased the debt burden on their populations.
Registering, in their own way, what is universally acknowledged as an intractable debt crisis in the poorer nations, the International Monetary Fund (IMF) warned that a serious banking crisis is likely to emerge (while ignoring the factors driving this scenario). ‘Our updated global bank stress test shows that, in a severely adverse scenario, up to 29 percent of emerging market banks would breach capital requirements’, the IMF wrote in October 2022.3 This means that the context of high debt, high inflation, and low growth rates (with lowered employment expectations) could lead to the collapse of a third of the banks in the poorer nations.
Neither the IMF nor the World Bank nor indeed any of the international financial institutions (IFIs) have any credible pathway out of this crisis. Indeed, the IMF report surrenders to reality as it tells central banks across the globe to ‘avoid a de-anchoring of inflation expectations’ and to ensure that ‘the tightening of financial conditions needs to be calibrated carefully, to aim at avoiding disorderly market conditions that could put financial stability unduly at risk’.4 The focus here is to keep ‘the market’ happy, while there is remarkably no care for the downward spiral of living conditions for the vast majority of the people on the planet. In its October 2022 Fiscal Monitor Report, subtitled Helping People Bounce Back, the IMF noted that while governments’ top priorities must be ‘to ensure everyone has access to affordable food and to protect low-income households from rising inflation’, they must not attempt ‘to limit price increases through price controls, subsidies, or tax cuts’, which would ‘be costly to the budget and ultimately ineffective’.5
In January 2023, the IMF’s World Economic Outlook predicted a slightly better, albeit ‘subpar’, growth forecast but warned of continued worries of debt distress in the poorer nations, writing that ‘The combination of high debt levels from the pandemic, lower growth, and higher borrowing costs exacerbates the vulnerability of these economies, especially those with significant near-term dollar financing needs’.6 The antidote to debt distress, according to the IMF, is ‘fiscal consolidation and growth-enhancing supply-side reforms’, namely more of the same old austerity-debt trap. If the governments of the poorer nations are told not to use these basic tools (which are used routinely in the richer nations), their only choice – as far as the IMF is concerned – is to borrow in order to provide even low levels of relief to the very poorest people in their countries. Effectively, the IMF has surrendered to the prevailing reality and offers the poorer nations no viable exit from a permanent debt crisis.
This dossier has been drafted with the knowledge that the permanent debt crisis besieging the poorer nations has not resulted from short-term market failures or from business cycles that will rebound, and that it is not fully a consequence of governments’ mismanagement of finances or deep-rooted corruption. Rather, our assessment of the debt crisis draws from an important speech given by Burkina Faso’s President Thomas Sankara (1949–1987) at the Organisation for African Unity in July 1987. ‘Debt’s origins come from colonialism’s origins. Those who lend us money are those who colonised us’, Sankara explained. ‘Debt is neocolonialism’, with the fiscal and monetary policies of many of the African states taken over by the ‘technical assassins’ of the IFIs. ‘Debt is a cleverly managed reconquest of Africa aimed at subjugating its growth and development through foreign rules’, he continued, with the IFIs setting policy by using the debt as an instrument to demand ‘structural adjustment’ of domestic finance ministries and central banks.7
Gro Harlem Brundtland, Norway’s former prime minister and then chair of the United Nations’ World Commission on Environment and Development (also known as the Brundtland Commission), came to the Organisation for African Unity meeting in Addis Ababa (Ethiopia) in 1987 to say that the entire debt of the poorer nations could not be repaid and should be forgiven. Sankara acknowledged the importance of the Brundtland Commission’s assessment and then said:
Debt cannot be repaid, first because if we don’t repay, lenders will not die. That is for sure. But if we repay, we are going to die. That is also for sure. Those who led us to indebtedness gambled as if in a casino. As long as they had gains, there was no debate. But now that they suffer losses, they demand repayment. And we talk about crisis. No, Mr. President, they played, they lost. That’s the rule of the game, and life goes on. We cannot repay because we don’t have any means to do so. We cannot pay because we are not responsible for this debt.8
One alternative to the debt crisis is a debt strike, which is what Cuba’s Fidel Castro began to raise in his speech at the Non-Aligned Movement meeting in New Delhi in 1983 and which was on the agenda for the Continental Dialogue on the Foreign Debt in Havana in August 1985. It is within this dynamic that Sankara spoke of the need for an ‘Addis Ababa united front against debt’.
The context for such a ‘united front against debt’ has returned, but the political will for it now is as low as it was then. However, the world is very different today than it was in the 1980s. Other alternatives have since presented themselves, such as those available through regional integration and through alternatives to the Western-backed IFIs (for example, financing from China and other large developing countries).9
This dossier opens with an introduction to the world of the IFIs – mainly the IMF – and their role in exacerbating the poverty brought on by colonialism and transforming it into a permanent debt crisis, and then moves into a deeper assessment of the contradictions of sovereign debt on the African continent. The final section carries a statement on the IMF-induced debt crisis by the Collective on African Political Economy and offers alternatives to IFI-led funding to manage the turbulence of debt.
The Fundamentalism of the IMF and the Permanent Debt Crisis
In 1919, John Maynard Keynes of the United Kingdom’s Treasury Department published a book that became a sensation. In the book, entitled The Economic Consequences of the Peace, Keynes observed that the Great War had ‘so shaken the system as to endanger the life of Europe itself’.10 The Treaty of Versailles, which ended the war, did not grasp the underlying problems that had led to the war and only cemented the victory of some countries against others. The treaty left structural problems intact, such as the ‘disordered finances’, in Keynes’ words, of many countries (not only Germany, which faced an enormous and unpayable reparations bill). The Wall Street Crash of 1929, the Sterling Crisis of 1931, and the Banking Panics of 1931–1933 revealed the underlying vulnerabilities of capitalism, with the ‘disordered finances’ being the spur towards the potential general collapse of the system. In 1936, Keynes published The General Theory of Employment, Interest, and Money, a manual to save capitalism by a theoretical plea for governments to use state resources to recycle profits and balance an unbalanceable system. Keynes, who dabbled in eugenics theory, did not extend his views on state intervention to protect the system in the British colonies and prevent the decline of their population’s living standards.
When the United States invited its allies to Bretton Woods (New Hampshire) in July 1944 to discuss how to manage the structural crises that contributed to the Second World War, Keynes – who was one of the main figures at this meeting – said that it would be ‘the most monstrous monkey house assembled for many years’, suggesting that ‘twenty one countries [that] have been invited’ – presenting a list of primarily colonised countries, from Guatemala and Liberia to Iraq and the Philippines – ‘clearly have nothing to contribute and will merely encumber the ground’.11 Instead, Keynes preferred that the two founder states of the Bretton Woods Conference, the United Kingdom and the United States, ‘settle the charter and the main details of the new body without being subjected to the delays and confused counsels of an international conference’, as he explained a few years earlier.12 In fact, Keynes (on behalf of the United Kingdom) and Harry Dexter White (on behalf of the United States) arrived at the meeting with two plans already drafted, which they put on the table and upon which the final Articles of Agreement for the International Monetary Fund as well as the International Bank for Reconstruction and Development (or the World Bank) were built. The other participants were largely onlookers.
Despite the limited input of most of the world, which was still under colonial rule, the purpose of the IMF as laid out in the Articles of Agreement was straightforward, none of it built to extend the power of the British imperial system. The main thrust of the articles was to assist the ‘expansion and balanced growth of international trade’ and to ‘contribute thereby to the promotion and maintenance of high levels of employment and real income and to the development of the productive resources of all members as primary objectives of economic policy’.13 To establish these ‘primary objectives’, the IMF was tasked with preventing any short-term problems from becoming long-term crises, such as by maintaining exchange rate stability and facilitating loans to prevent balance-of-payments spirals ‘without resorting to measures destructive to national or international prosperity’. When the former colonial countries won their freedom, most of them became members of the IMF based on the Articles of Agreement, and in 1961, the IMF created its Africa Department. Until the Third World Debt Crisis that began to spiral with Mexico’s default in 1982, the IMF had primarily operated by providing short-term financing in a relatively modest fashion through the Compensatory Financing Facility (1963) and the Buffer Stock Financing Facility (1969).14
In the aftermath of Mexico’s default, the IMF conducted what its managing director, Michel Camdessus, called the ‘silent revolution’.15Against its manifest purpose, the IMF began to respond to requests for short-term bridge financing by demanding that countries radically change their domestic economic policies as a condition for approval. Through their new programmes, the Structural Adjustment Facility (1986), and then the Enhanced Structural Adjustment Facility (1987), the IMF put a singular recipe on the table: privatise the economy, including the state sector; commodify areas of human life that had up to that point been in the public domain; terminate any government deficit financing; and dissolve any barriers on foreign capital investment and trade (such as subsidies and tariffs). The IMF had experimented with these measures in Bolivia, Chile, and Peru in the 1950s with limited success before turning them into the basis for their policy not towards all countries, but specifically to be used against states in Africa, Asia, and Latin America, which struggled with an international economic system shaped by colonialism and capitalism. These were the countries that had championed the formation of the UN Conference on Trade and Development (UNCTAD) in 1964 to advance their own proposals to exit the neocolonial world order, proposals that were passed by the UN General Assembly in 1974 as the New International Economic Order (NIEO). The new IMF policy emerged in contest against the possibility of an NIEO, since rather than allow for a better deal for raw material prices or for tariff-subsidy arrangements, it demanded the withdrawal of all these anti-colonial schemes. Even Raghuram Rajan, the IMF’s own chief economist from 2003 to 2007, wrote in his book Fault Lines (2010) that the IMF’s policies appeared as a ‘new form of financial colonialism’.16
The IMF’s ‘silent revolution’ intensified the crisis faced by the poorer nations, driving them into a spiral of indebtedness and poverty. The general formula for this spiral is as follows:
- Countries go into short-term balance-of-payments debt because of their lack of capital – much of it stolen during the colonial period – and their reliance upon borrowing to conduct (often expensive) capital improvements in their countries (some of which are in the raw material extraction sector, thereby operating as a subsidy for foreign mining companies).
- The IMF arrives and informs the finance ministries that government spending for education, healthcare, and other social development projects must be cut in order to prioritise payments to wealthy bondholders (in the London Club) and to governments – mostly the old colonial states – (in the Paris Club) who have lent them money.
- To pay the debt servicing on these loans, the poorer nations cut their government spending, thereby impoverishing their people further, and export more of their cheapened raw materials (rather than more profitable finished products). When countries start to export more and more primary commodities, this produces a price war that leads to a steep decline in the revenues gained from the volume of exports.
- With weakened revenues from imports, the poorer nations must continue to cut their social spending, ramp up their sales of raw materials and public assets, and borrow more money from external private and governmental sources… just to pay off the interest on their ballooning debt.
- The imperative of ‘exchange rate stability’ prevents governments in the poorer nations from exercising any effective monetary policy – including implementing capital controls – while their fiscal policy is already eviscerated by balanced budget demands from the IMF, social spending cuts, and pressure from wealthy bondholders to ‘reform’ (i.e., surrender) their tax policy.
In 2016, senior members of the IMF’s research department published an article called ‘Neoliberalism: Oversold?’, which argued that the ‘adverse feedback loop’ set in motion by austerity, followed by increased inequality and then yet more austerity, had to be broken by a less rigid, less fundamentalist approach to ‘liberalisation’ and neoliberalism.17 There was even a suggestion of ‘greater acceptance of [capital] controls to deal with the volatility of capital flows’. While there was a decline in the conditions that the IMF required to receive their loans over the course of the decade before this paper was published, there is no evidence of any qualitative change in IMF policy.18
Guinea, for instance – a country that has at least a third of the world’s bauxite – entered the IMF rollercoaster in 2011 and immediately became trapped in the debt-austerity cycle.19 In 2014, the Guinean government of Alpha Condé wrote to the IMF that the ‘tight fiscal and monetary policy’ had led to a ‘reduction in spending, including on domestic investment’, which made it impossible for Guinea ‘to respect the indicative targets for spending in priority sectors’.20 In other words, Guinea borrowed to try and exit a crisis, but the borrowing itself led to cuts in social spending and deepened its crisis. In 2019–2020, the country experienced a cycle of protests sparked both by Condé’s attempt to change the constitution as well as the worsened economic situation. A UNICEF report found that, in 2019, twenty-five very poor countries spent more on debt servicing than on education, health, and social protection combined. Sixteen of those countries are on the African continent.21
In the early months of the pandemic in 2020, the IMF offered to open up new windows for borrowing that they said would come without conditionalities.22
The G20 Debt Service Suspension Initiative and other such offers to pause debt payments suggested that the poorer nations would receive assistance to prevent total economic collapse and to gain access to vaccines. However, Oxfam found that thirteen of the fifteen IMF loan programmes during the second year of the pandemic (2021) required ‘new austerity measures such as taxes on food and fuel or spending cuts that could put vital public services at risk’.23 The Commitment to Reducing Inequality Index reveals that fourteen out of the sixteen countries in West Africa planned to cut their budgets by a total of $26.8 billion in 2021 to contain haemorrhaging national debt crises and that these policies have been encouraged by the IMF’s COVID-19 loans.24
The evidence is clear: the IMF not only engineers austerity-driven debt crises, but its policies are designed to ensure and manage a permanent debt crisis, not to erase debt.
Africa’s Sovereign Debt Crisis
In 2009, the Zambian-born economist Dambisa Moyo published the instant bestseller Dead Aid.25 Moyo’s main argument in the book was that there was little to show for the hundreds of billions of dollars in foreign aid that had been given to the African continent since 1970. Rather than spurring development, she said, aid had financed grand-scale corruption and civil wars, which in